“How do I know my funder will actually negotiate with you?” We hear that question from business owners who are still making their merchant cash advance (MCA) payments but are finding it harder to cover payroll or pay suppliers on time. It’s a fair question. If the funder is still getting paid, why would it consider changing the terms?
In our experience, getting a funder to talk has rarely been the difficult part. The work is finding a payment the business can keep making and the funder is willing to accept.
Why funders are willing to talk to us
Some escrow-based relief programs ask you to stop paying the funder and start making weekly deposits instead. You may be sending money out every week, but until it reaches the funder, those deposits aren’t paying down the advance. The funder can keep pursuing payment while you wait for the account to build up.
Apple Debt Relief doesn’t hold settlement funds in escrow or collect weekly deposits. If you’re still paying your funder, we don’t require you to stop to work with us. If you approve new terms, you pay the funder directly.
Funders familiar with us know that’s how we work. We contact them directly, explain what’s putting pressure on the business, and propose a payment based on its cash flow. If the debit is still clearing but it’s getting harder to make payroll or pay vendors, we can start that conversation before you miss a payment.
Sometimes an owner tells us their funder has already said, “We don’t work with debt relief companies.” We explain how our arrangement works up front: we’re asking to discuss the payment terms, and the owner still decides what to accept. Then we get to the reason for the call: what changed at the business and what it can keep paying.
What goes into a payment proposal
We look at what’s coming in, what the business needs to keep operating, and how much it’s already paying on each advance. If several funders are pulling from the same account, a reduction from one only helps if the remaining payments still leave enough for expenses like payroll and inventory.
Say a funder offers a smaller weekly debit for one month. That could give the business time to get through a slow period. But if the original debit resumes before sales recover, the same shortfall can come back. When we review terms with you, we look at when the lower payment ends and whether any amounts deferred during that month have to be made up later. Those details can change what the business actually owes in the weeks ahead.
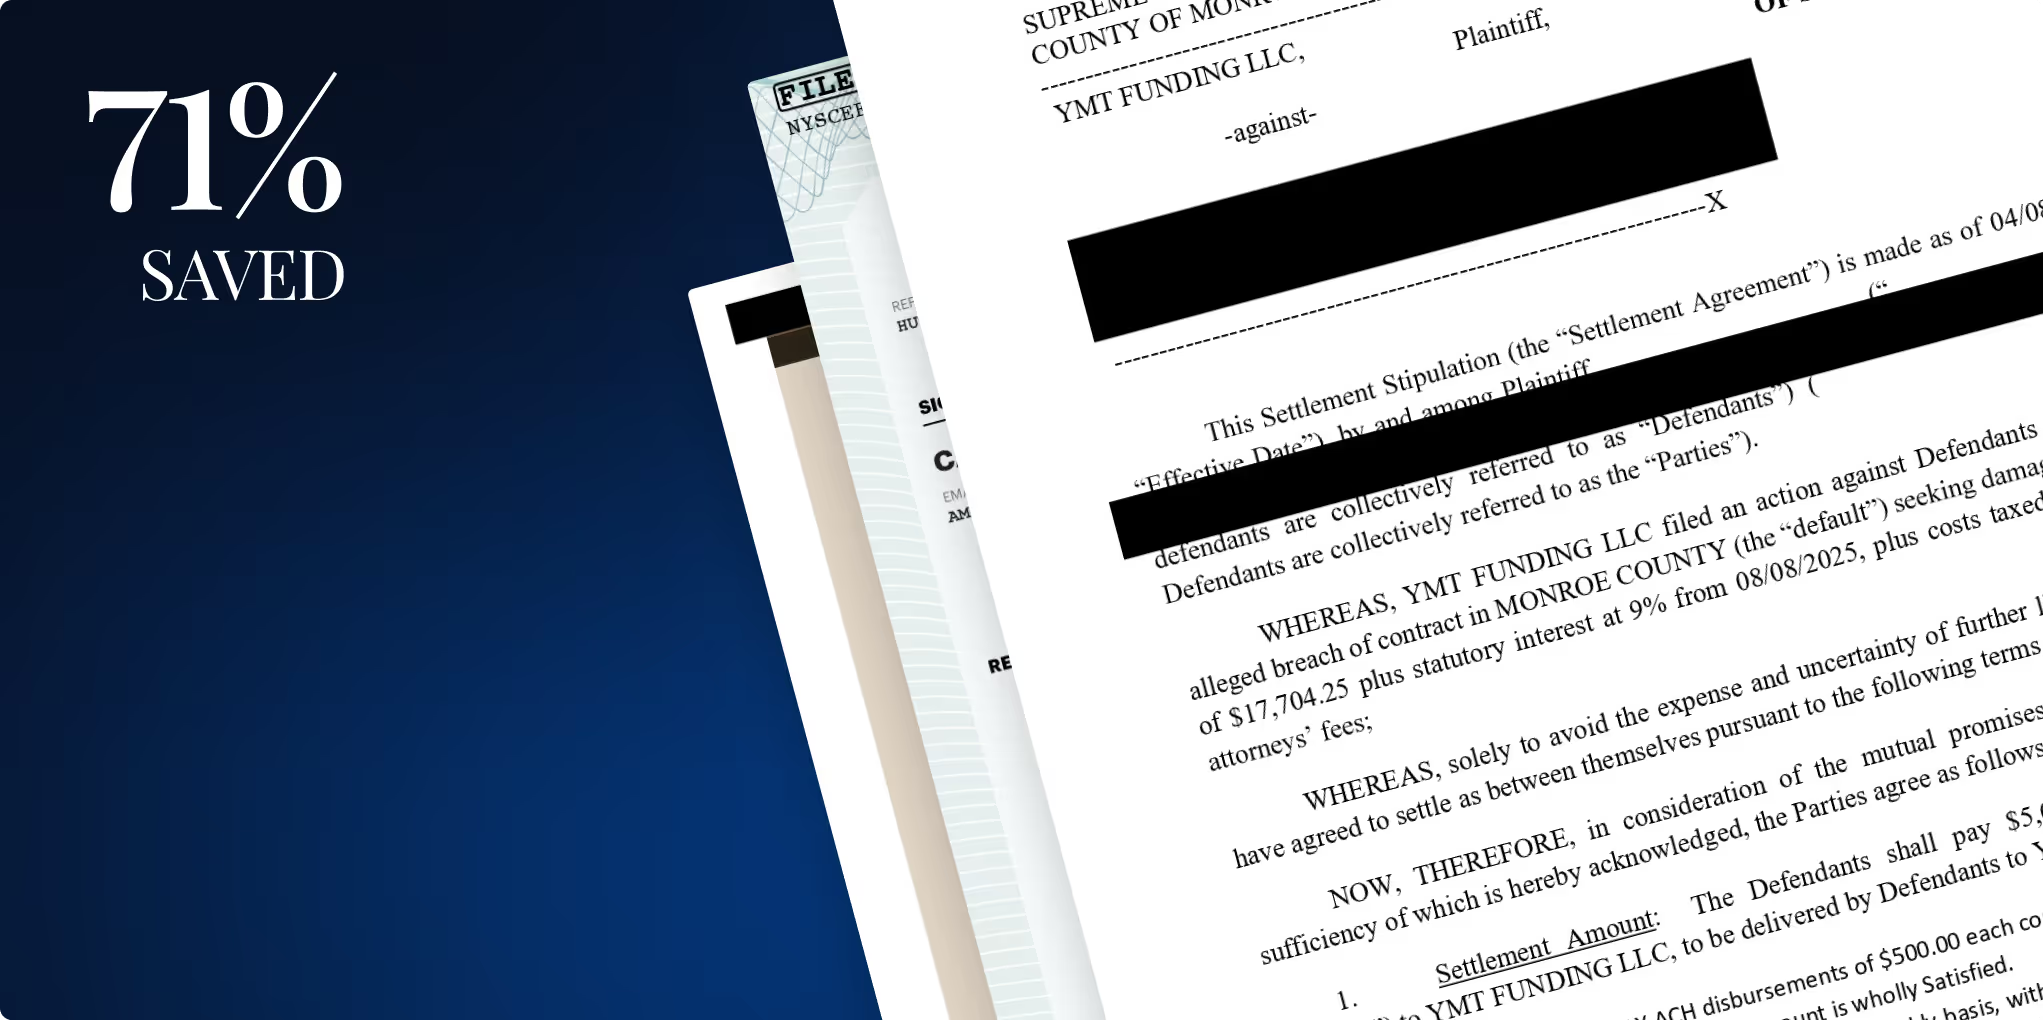
Getting a response is one step. If the terms still don’t fit the business, you can decline them. We negotiate on your behalf, and you approve any offer before it’s accepted.
Discussing your specific funder
If you want to know whether we’ve negotiated with your funder before, ask on the first call. Use the name shown on your agreement. We can talk through our experience and what we’d want to review before contacting them. Prior experience gives us a starting point; your payment history and cash flow shape what we propose now.
If you’re still paying but the withdrawals are getting harder to cover, read about MCA payment help before default or request a free review. Start with who you’re paying, how much comes out, and how often.